Building FP&A From Absolute Zero: Katelyn Stienen on Budgets, Business Partnership, and the Stories Behind the Numbers
What would you do if you walked into a five-year-old company with more than 170 legal entities, roughly 10,000 budget lines, no FP&A planning system, department heads who had never worked with a structured P&L, and tax rules capable of changing while you were still building the budget?
I think I’d need coffee first.
Probably several.
That’s roughly the situation Katelyn Stienen walked into.
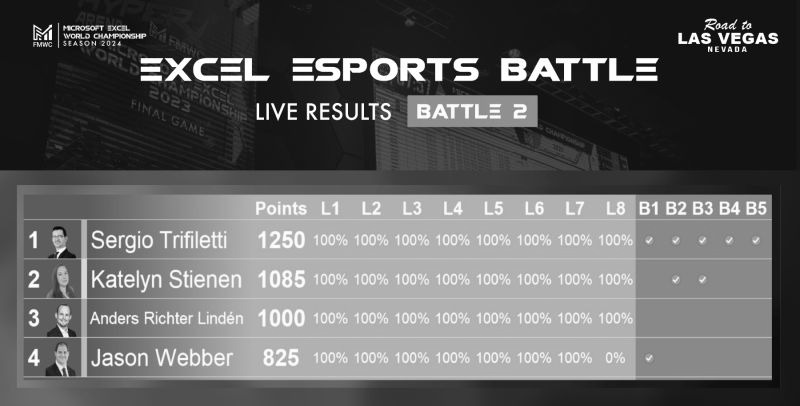
Katelyn is a Chartered Financial Modeler, an FP&A leader, and a top-16 finisher in the Excel World Championship. Yes, there is an Excel World Championship. Yes, it airs on ESPN.
As I said during our conversation, apparently we’re not all just a bunch of nerds. We’re on ESPN now.
But here’s what made my conversation with Katelyn interesting.
For someone who is extraordinarily good at Excel, almost none of the hardest problems she described were Excel problems.
They were people problems.
They were communication problems.
They were problems created when Finance and Operations were looking at the same business through completely different lenses.
And Katelyn was trying to build an FP&A function in the middle of all of it. Pasted text
Meet Katelyn Stienen
Katelyn has had an unusual vantage point on what a finance function can look like at very different stages of maturity.
She has worked inside companies with long-established processes and is now helping build structure inside a much younger organization.
That contrast matters.
At an older company, a capital request process may have existed for decades. There are forms, approval levels, financial-return requirements, and probably at least one rule nobody particularly enjoys.
But those rules usually have a history.
As Katelyn pointed out, somewhere along the way somebody probably approved a project that didn’t go particularly well. Eventually a process appeared around it.
Then she moved into an environment where she wasn’t improving generations of accumulated Finance infrastructure.
She was building.
Her description of that realization was one of my favorite lines from the episode:
“I’m not reformulating. I’m starting at absolute zero.”
That’s a very different FP&A job.
And I think there are some useful lessons in what she did next.
Before You Build a Budget, Make Sure Everyone Knows What a Budget Is
This sounds almost too basic.
It wasn’t.
Katelyn came in trying to bring more detail to planning. Instead of saying SG&A would be a few hundred thousand dollars, she wanted to understand marketing, payroll, utilities, employee engagement, and the other individual lines underneath it.
Perfectly normal FP&A work.
Except there was a problem.
The department heads hadn’t necessarily been through a formal budgeting process before.
Katelyn created a template using historical spending and estimates as a starting point.
Then someone called her.
“You cut the employee engagement budget.”
Katelyn’s reaction was essentially: I did?
She hadn’t cut anything.
She had created a starting point for a conversation.
The person receiving it thought Finance had handed down the final answer.
That’s when Katelyn realized the first job wasn’t building a better budget.
It was creating a shared understanding of what the budget actually meant.
Her first question became:
“Is everyone working from the same vantage point?”
That’s a question I’d steal.
Because Finance can spend weeks designing a beautiful process and still fail if the people participating in it don’t understand what they’re being asked to do.
FP&A Has to Learn the Business Before It Can Model the Business
One thing came through repeatedly in my conversation with Katelyn: she likes Operations.
She called herself an “ops nerd at heart” who happens to be good at Finance.
I understand this completely.
Some of the best FP&A work happens when you wander far enough away from Finance to understand how the company actually works.
Katelyn’s current business includes both retail operations and cultivation facilities, which function much like manufacturing plants. Some operational teams had already created their own budgets and expense-tracking processes before formal FP&A existed.
That was useful.
It also created another problem.
Operations had one set of numbers.
Leadership had another.
There was no connection between them.
Katelyn described the solution simply: the budget the operators were actually managing would now connect to what the company communicated upward.
No more Playbook A for Operations and Playbook B for everyone else.
This sounds obvious when you read it.
It becomes considerably less obvious when you’re inside a company and both playbooks have been operating independently for three years.
Get Finance Into the Conversation Earlier
Katelyn saw another important difference across the companies where she’d worked.
At one organization, Finance was involved early in capital projects.
Engineers might understand exactly what a new project would change operationally, while Finance could help translate those changes into the complete economics.
At another company, people sometimes developed savings projects and calculated the financial benefits themselves. Finance came in later to validate the numbers.
Katelyn prefers the first approach.
So do I.
Someone may tell you a project reduces labor expense.
They may be completely right.
But maybe it also increases utilities.
Maybe maintenance changes.
Maybe overhead gets allocated differently.
Maybe there are costs the project owner doesn’t see because they aren’t responsible for them.
That’s not because Operations is bad at Finance.
They’re not supposed to be Finance.
Katelyn put it this way:
“Why can’t Finance just be the one to help you make sure that what you’re talking about makes sense?”
That’s business partnering without the corporate vocabulary.
Don’t wait until somebody has fallen in love with a project and built an entire business case before Finance arrives to explain that half the savings aren’t actually savings.
Sit down earlier.
It’s usually a nicer conversation.
A Bottoms-Up Budget Gives You Something to Talk About
Katelyn is firmly in the bottoms-up-budget camp.
Not because top-down planning is useless.
She pointed out that top-down planning can be extremely useful when you need speed, directional information, or an early indication that sales, cash flow, or another major driver may be moving the wrong way.
But bottoms-up planning gives Finance something else:
specificity.
If a team said it expected to spend $20,000 a month and is now spending $40,000, there’s a conversation to have.
And that conversation shouldn’t begin with punishment.
Maybe the team needs more resources.
Maybe the original assumption was wrong.
Maybe conditions changed.
Maybe they’re spending more because revenue is growing.
The budget gives you a reference point from which to ask why.
That distinction became especially important when Katelyn and one of her finance directors approached Sales about an area that was behind plan.
The initial response was defensive.
The Finance team’s message was simple:
“We’re just trying to figure out what happened. We’re not trying to blame you.”
That changed the conversation.
I wish more Finance teams understood how much those few words matter.
If every question from Finance feels like the beginning of a trial, people learn very quickly to stop volunteering information.
That’s a terrible forecasting system.
Sometimes the Most Important Information Never Makes It Into Finance
Katelyn gave a perfect example.
The business had two facilities.
Operationally, it made more sense for one facility to package product for the other, so the team changed the process.
Reasonable decision.
Nobody told Finance.
Finance continued costing the product as though it were being packaged at the original facility.
Nothing was “wrong” with the Finance model in the traditional sense.
The business had changed.
The model hadn’t been told.
I see versions of this all the time.
Finance can have immaculate formulas and still be wrong because somebody changed what happens on Tuesday afternoon and didn’t think it was something Finance needed to know.
That’s why business partnering matters.
You can’t model information you never receive.
Now Add 170+ Entities and Changing Regulation
As though the planning problem wasn’t interesting enough, Katelyn works in the cannabis industry.
That adds an entirely different layer of complexity.
Her organization operates across multiple states, with individual entities facing different market conditions and regulatory requirements. A recreational market may behave differently from a medical-only market. Product availability can differ. Marketing rules can differ. And federal and state requirements don’t always align neatly.
Katelyn compared it to international business: each state can begin to feel like its own country.
So how do you forecast in an environment where the rules themselves may move?
You run scenarios.
But you also talk to people.
Katelyn relies heavily on leaders who have spent years in the industry and understand the market in ways a spreadsheet never will.
She listens to what they’re seeing, what they believe is changing, and what they’re hearing from the market.
Then she does the Finance part.
This was probably my favorite description of FP&A from the entire conversation:
“Getting to take the anecdotes, getting to take the stories people tell you and say, ‘What does that actually mean to the numbers?’”
That’s FP&A.
Not all of it, obviously.
But a lot more of it than we sometimes admit.
Finance Is Part Private Investigator
At one point I told Katelyn that Finance people might need little PI badges.
I stand by this.
You’re listening to what management says.
You’re listening to Operations.
You’re watching customers.
You’re looking at the market.
You’re checking the numbers.
And then you’re trying to figure out whether all of those things tell the same story.
Sometimes they don’t.
That’s when the work gets interesting.
Katelyn described her approach with capital projects similarly. She doesn’t need an engineer to become a financial modeler.
She wants the engineer to tell her what will change.
One fewer operator?
More wastewater?
Different maintenance?
Changed production?
Tell Finance the story.
Finance can put numbers against it.
As Katelyn said:
“Once you get them talking, you can usually learn a lot.”
That’s a much better description of business partnering than putting “strategic business partner” on a job description and hoping for the best.
When Is a Company Ready for FP&A Software?
Katelyn’s experience also challenged another assumption: that smaller companies should wait to implement planning software.
Her answer was more nuanced.
Company size alone isn’t the deciding factor.
She’d look first at whether the company has enough Finance capability to own and manage the system, whether the business has enough complexity to justify it, and whether the underlying ERP foundation is solid.
If you’ve got a very simple company with one product and a handful of cost lines, maybe you don’t need it yet.
But complexity can arrive long before a company becomes “large.”
And waiting until the company explodes in size can create its own problem.
As Katelyn put it, it’s better to think about the infrastructure while you’re growing than suddenly have a booming company and try to “shove it into a software.”
I enjoyed that description because I’ve seen the corporate version of shoving something into software.
It usually involves a lot of meetings.
What Changed Once the Planning System Was in Place?
For Katelyn, one of the biggest changes was access to detail.
Her team could begin looking at budget-to-actual variance at the individual GL level across a very complicated entity structure.
Questions changed.
Instead of:
Can we get the numbers?
Finance could start asking:
What’s actually happening inside the numbers?
That’s an enormous shift.
Katelyn described being able to pull apart expense accounts with department heads and ask whether the spending made sense.
Advertising was one example.
Instead of simply seeing a large advertising number, they could break apart billboards, events, and other spending and ask:
Are the billboards working?
Are they in the right locations?
Does the spend make sense?
Maybe an expense increasing is bad.
Maybe revenue is increasing alongside it and the relationship makes perfect sense.
You don’t know until you look underneath the total.
This is the point of better Finance infrastructure that gets lost in software conversations.
The goal isn’t to retrieve a number five minutes faster because five minutes is inherently exciting.
The goal is to spend less time finding the number and more time deciding what it means.
Katelyn Would Like You to Stop Using VLOOKUP
I would be failing you if I wrote an article about an Excel World Championship finalist and didn’t ask about Excel.
Katelyn’s favorite function?
XLOOKUP.
Her advice was not subtle:
“If you’re still using VLOOKUP, get rid of it.”
I admitted that I was fairly late to XLOOKUP myself.
This is a safe space.
She also thinks Finance teams underuse LET, particularly because it can make complicated formulas easier to build and understand.
Katelyn is operating at a level where Excel apparently becomes a competitive sport.
I am operating at a level where I occasionally discover a function everyone else has apparently known about for five years.
We both survive.
Even an Excel Expert Is Using AI
Katelyn also uses AI in her work, including to help with SQL.
She hasn’t historically needed to be a SQL expert, so she’ll give AI an existing query, explain what she’s trying to accomplish, and ask it to help.
Does it always work?
No.
Which may be the most reassuring answer possible.
She described AI as a useful copilot that can sometimes correct itself when she tells it the first answer didn’t work.
She has even renamed Claude.
When it’s helpful, it’s Claudia.
When it starts fighting with her unnecessarily, it goes back to Claude.
This may be the AI governance framework I’ve been looking for.
Kill the Annual Budget?
During rapid fire, I asked Katelyn whether she’d keep or kill the annual budget.
Her answer:
“I kind of want to kill it.”
Her current organization is budgeting every six months, while she strongly favors maintaining a monthly forecast.
She made a point Finance people know well: by September, how many people are really managing the business based on a budget they wrote the previous year?
The world has moved.
The business has moved.
Your forecast should have moved with it.
That doesn’t make the annual budget useless in every company.
It does mean Finance should be clear about what job the budget is supposed to perform once reality starts ignoring it.
Reality has a bad habit of doing that.
And Talk About Cash More
When I asked Katelyn which report or KPI she’d kill, she cheated.
Instead, she told me which one she’d elevate.
Cash flow.
She sees organizations going to EBITDA, income, and other performance measures first while cash appears later on the dashboard.
Her view was much simpler:
“People should talk about cash flow more.”
Hard to argue with that one.
Eventually, cash becomes a remarkably persuasive KPI.
Would You Rather Be Lucky or Good?
I ended the rapid-fire section by asking Katelyn for one question a listener could take back to their Finance team.
Her answer was about forecast accuracy.
How much inaccuracy are you willing to accept?
Then she reframed it:
“Would you rather be lucky or would you rather be good?”
Suppose your forecast lands exactly on the actual result.
Wonderful.
Can you explain why?
Now suppose the forecast misses.
Can you explain every important driver behind the miss?
Katelyn would rather be able to explain the miss.
Her goal isn’t pretending a forecast can perfectly predict an uncertain future.
It’s understanding what drove the outcome.
As she explained:
“I always aim to be able to explain why I’m off.”
That’s a more sophisticated view of forecast quality than celebrating a small error percentage without understanding how you got there.
A forecast can be right for the wrong reasons.
That’s luck.
Eventually luck sends an invoice.
The Best Excel Person in the Room Kept Coming Back to People
At the end of our conversation, Katelyn offered one final piece of advice.
Before putting numbers in front of someone outside Finance, understand their background.
What exposure have they had to Finance before?
What do they understand?
What don’t they?
Meet them there.
It makes the conversation better.
And that’s when something clicked for me.
Katelyn is one of the best Excel users in the world.
Yet almost none of the problems we spent an hour discussing were really spreadsheet problems.
Operations had one budget.
Leadership had another.
She connected them by getting people together.
A process changed between two facilities.
Finance didn’t know.
The solution was communication.
Sales became defensive when Finance questioned performance.
The Finance team explained they were trying to understand, not assign blame.
The conversation changed.
The planning system mattered. Excel mattered. The ERP mattered.
But the hardest complexity wasn’t living inside the spreadsheet.
It was living in the gaps between people.
So if you want something practical to take from Katelyn’s story, I’d start here:
Go find your two playbooks.
Find the number where leadership believes one thing while the people actually running the business are managing toward something else.
I suspect there’s one somewhere.
Then get those people into the same room.
You may not need a better formula yet.
You may just need a conversation.