Private Colleges Have a Revenue Problem That Looks Familiar
I read today’s story about the pressure facing private colleges and had an immediate finance reaction:
I’ve seen this problem before.
Not necessarily at a university.
In businesses.
The customer base changes. Buyers become more price-sensitive. Lower-cost alternatives improve. The organization still has a cost structure built for the market it used to have.
Then everyone starts looking for growth.
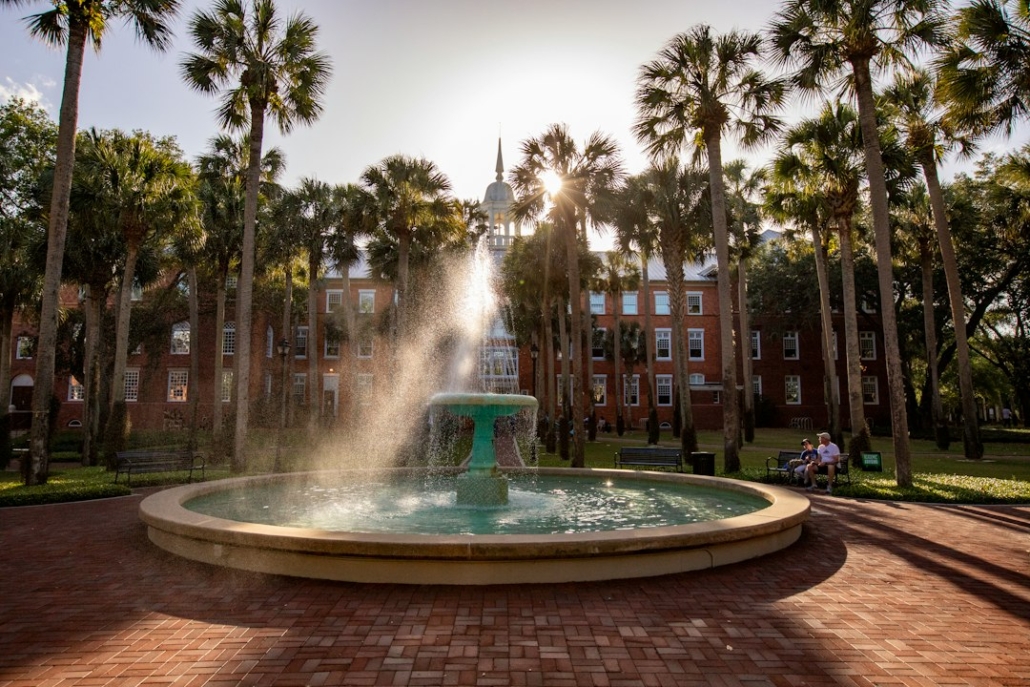
Private colleges are facing a shrinking pool of traditional college-age students while families are asking harder questions about cost and value. Stetson University in DeLand is among the Central Florida institutions discussed in today’s Orlando Business Journal coverage. The report is here.
The experts quoted in the story say there is no silver bullet.
That sounds right to me.
Silver bullets are suspiciously rare once somebody opens the income statement.
The demographic problem is the part I’d put at the top of the model
If I were building the forecast for a private college, I wouldn’t start with tuition revenue.
I’d start with people.
How many prospective students are actually going to exist in the markets we recruit from?
How many apply?
How many get admitted?
How many enroll?
How many stay?
Because if the traditional college-age population is shrinking, I don’t get to solve that in Excel by typing 4% into the enrollment-growth cell.
I mean, technically I can.
Excel has never once stopped me from making a bad assumption.
That’s one of its more dangerous qualities.
Demographics are an operating driver. If the driver changes, the plan has to acknowledge it.
As a parent, I understand the second problem immediately
Families are asking whether college is worth the price.
I don’t think colleges can treat that as a messaging problem.
It’s a value question.
Parents are looking at tuition, housing, fees and years of total cost, then looking at the likely outcome on the other side.
We do this while raising children who can somehow lose a water bottle between the kitchen and the car.
It’s an extraordinary combination of long-term capital allocation and very short-term operational risk.
But the question is rational:
What are we paying for, and what does the student receive?
If families become less convinced by the answer, discounting alone doesn’t solve it.
It may help close an enrollment gap.
It doesn’t necessarily repair the underlying value proposition.
Sticker price isn’t the number I’d manage
This is another place my finance brain goes immediately.
A private college can publish one tuition number and collect something very different after institutional aid.
So I would care deeply about net tuition revenue per student.
I’ve seen the corporate version of this enough times.
We have a list price.
Then a discount.
Then a strategic discount.
Then an exception because this customer is “important.”
Eventually Finance asks why average revenue looks like it has never met the pricing sheet.
The economics live in what customers actually pay.
For colleges, I’d want to see enrollment and discount rate together. A bigger incoming class doesn’t impress me very much if we had to give away substantially more revenue to get it.
The fixed-cost structure is what makes me nervous
This is where the problem starts looking very familiar.
If enrollment falls 7%, the campus does not become 7% smaller on Tuesday.
The buildings remain.
Faculty and staff remain.
Maintenance remains.
Technology remains.
Insurance remains.
Administration remains.
Revenue can move faster than the cost base.
I’ve watched this happen in businesses, and it creates a particularly unpleasant kind of forecast meeting.
The top line has accepted reality.
The expense plan has not received the memo.
That’s why I’d want to know which costs are truly fixed, which are step-fixed, which can move, and how long each takes to change.
Not after enrollment misses.
Before.
I would be careful with the “find more students” solution
The obvious response to a shrinking traditional market is to find new markets.
Adult learners. Graduate students. Online programs. International students. New geographies. New degrees.
Some of that may be exactly right.
But this is where I would start annoying everyone with contribution margins.
Does the new program actually contribute?
What does it cost to acquire the student?
What faculty and infrastructure does it require?
How much institutional aid is involved?
Does it use existing capacity or create another layer of cost?
I’ve seen organizations grow their way into more complexity without growing their way into more economics.
Revenue is not automatically helpful just because it is new.
My children understand this instinctively. Every additional activity sounds wonderful until someone remembers there are only seven days in a week and apparently I am the transportation department.
I think the better question is what the institution would build today
This is the part of the story that interests me most.
When a market changes structurally, I don’t love asking, “How do we get back to the old numbers?”
I would rather ask:
If we were designing this institution around the students, economics and competition we have now, what would it look like?
Which programs would we expand?
Which would we stop subsidizing?
What would we charge?
Who are we actually trying to serve?
What experience is worth paying a premium for?
What parts of the cost structure exist because they’re necessary, and what parts exist because they’ve been there since everyone owned a PalmPilot?
That last category tends to be larger than organizations expect.
This is a driver-based planning problem
If I were helping a college build its plan, I wouldn’t let tuition revenue sit at the top of the model as one heroic assumption.
I’d want applications, admits, yield, retention, student mix, tuition, aid, net tuition per student, housing, program economics and capacity.
Then I’d build scenarios around the drivers that can actually move.
That’s why I like driver-based planning.
It forces the financial forecast to explain what the business—or institution—has to do operationally for the number to happen.
“Revenue grows 5%” is easy.
“Here are the students, retention rates, prices and discounts required to produce 5%” is where the conversation starts getting useful.
I don’t think colleges are uniquely bad at this
That’s probably my biggest takeaway.
It’s tempting to read higher-education stories as though universities have some strange economics nobody else could possibly understand.
I see something much more ordinary.
A mature organization.
A changing customer.
A high fixed-cost base.
Pressure on price.
New competitors.
Management trying to figure out which parts of the old model still work.
I’ve seen versions of that story in plenty of industries.
The campus makes it look different.
The finance problem doesn’t.
And no, I don’t think there’s a silver bullet.
I think there are a handful of operating drivers, some uncomfortable choices, and probably one program everyone insists is “strategic” despite nobody being able to explain the economics.
Now that feels familiar.
I write more about the operating drivers behind financial results in my FP&A Library. If your organization needs help turning those drivers into a usable plan, see my FP&A consulting work.


Leave a Reply
Want to join the discussion?Feel free to contribute!